

In partnership with NEXT.io, leading iGaming analytics provider Blask analyses the iGaming industry performance of South Africa between H1 2023 and H1 2024.
The first half of 2024 witnessed significant changes compared to the same period in 2023. This analysis of South Africa’s iGaming industry explores key shifts, trends, and performance metrics of the top brands, highlighting the overall market dynamics.
Key iGaming market trends and shifts in South Africa
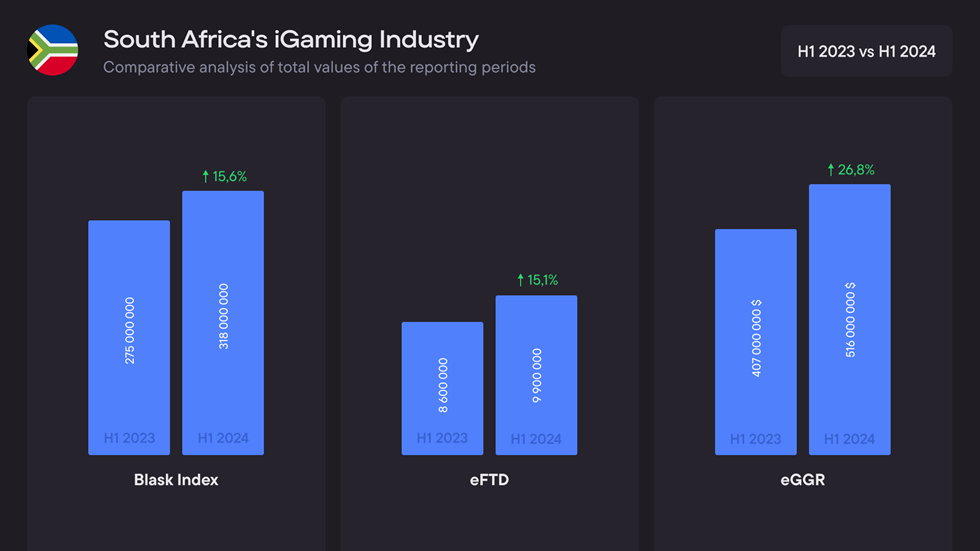
Blask Index
The Blask Index is a quantitative indicator that estimates the size of the iGaming market in various countries and shows the market share of each brand.
The Index works as a comprehensive metric to gauge market sentiment and overall health, similar to how the Nasdaq Composite and Dow Jones Industrial Average act as barometers for the US stock market.
Blask Index transforms public search data into a ready-to-use chart, with one-hour updates. It assigns market share to individual brands based on their search volume and calculates the total market size by aggregating all brand searches within a given country.
Below is the Blask Index score for South Africa in H1 2024:
- • Peak: 57m in March
- • Lowest: 49m in June
- • Average: 53m
- • Total: 318m
Compared to H1 2023:
- • Peak: 50m in April
- • Lowest: 43m in January
- • Average: 46m
- • Total: 275m
This represents a 15.6% year-on-year increase in the total Blask Index score.
Expected First Time Deposits (eFTD)
eFTD is a metric that estimates the number of new players making their first deposit on an iGaming platform, which is calculated using traffic data and conversion rates, providing insights into player acquisition.
The eFTD for South Africa in H1 2024:
- • Peak: 1.8m in March
- • Lowest: 1.5m in June
- • Average: 1.6m
- • Total: 9.9m
Compared to H1 2023:
- • Peak: 1.6m in April
- • Lowest: 1.3m in January
- • Average: 1.4m
- • Total: 8.6m
This represents a 15.1% year-over-year increase in total eFTD.
Expected Gross Gaming Revenue (eGGR)
eGGR is an approximation of the total amount of money wagered by players minus the winnings paid out, which helps assess the financial performance of iGaming operators without access to their internal data.
The eGGR for South Africa in H1 2024:
- • Peak: $88m in March
- • Lowest: $84m in June
- • Average: $85m
- • Total: $516m
Compared to H1 2023:
- • Peak: $71m in April
- • Lowest: $63m in January
- • Average: $67.8m
- • Total: $407m
This represents a 26.8% year-over-year increase in total eGGR.
Market share of top iGaming brands in South Africa
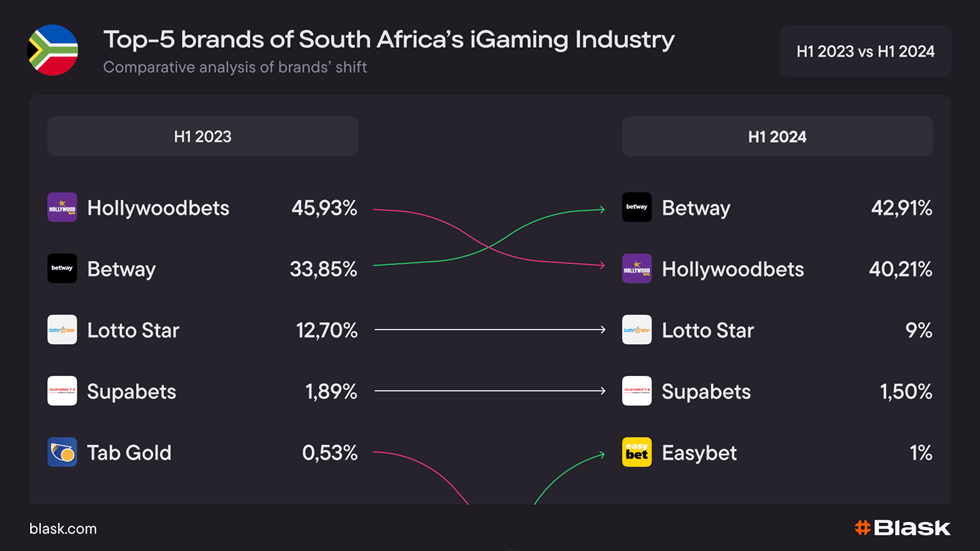
Blask analysed the shifts in market share of the top five iGaming brands in South Africa between H1 2023 and H1 2024.
Market Share for top five brands in South Aftica in H1 2024:
- • Betway: 42.9%
- • Hollywoodbets: 40.2%
- • Lotto Star: 9%
- • Supabets: 1.5%
- • EasyBet: 1%
Compared to H1 2023:
- • Hollywoodbets: 45.9%
- • Betway: 33.9%
- • Lotto Star: 12.7%
- • Supabets: 1.9%
- • Tab Gold: 0.5%
Tab Gold slipped from the top five position in H1 2024, with a 0.41% Market Share, while EasyBet reached the top five following a H1 2023 Market Share of 0.18%.
Performance of top three iGaming brands in South Africa
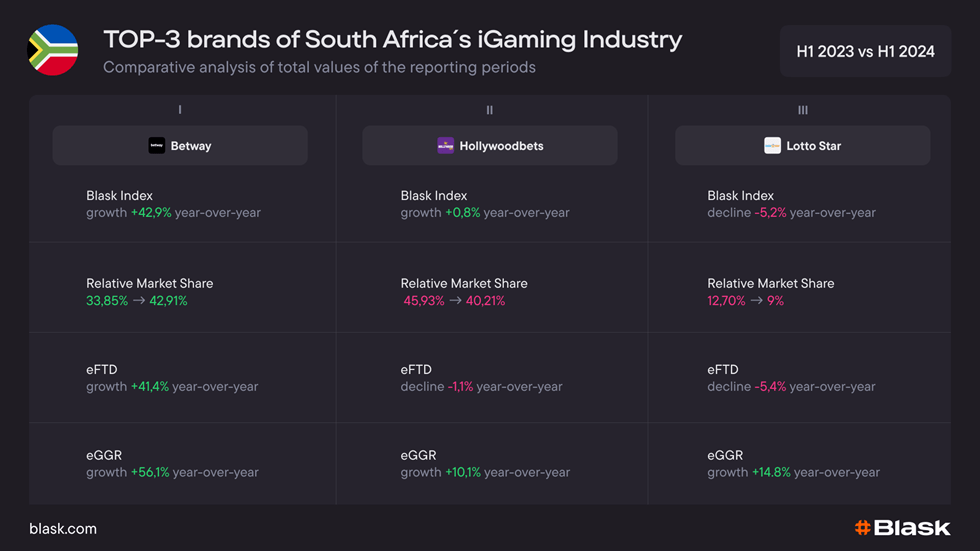
Using Blask, the year-over-year performance of the top three iGaming brands was also analysed.
1. Betway
- Blask Index: Increased from 98m in H1 2023 to 140m in H1 2024 (+42.9%).
- Market Share: Increased from 33.85% in H1 2023 to 42.91% in H1 2024 (+26.7%)
- eFTD: Increased from 3m in H1 2023 to 4.2m in H1 2024 (+41.4% ).
- eGGR: Increased from $132m in H1 2023 to $206m in H1 2024 (+56.1%).
2. Hollywoodbets
- Blask Index: Increased from 126m in H1 2023 to 127m in H1 2024 (+0.8%).
- Market Share: Decreased from 45.93% in H1 2023 to 40.21% in H1 2024 (-12.45%)
- eFTD: Decreased from 3.9m in H1 2023 to 3.8m in H1 2024 (-1.1%).
- eGGR: Increased from $188m in H1 2023 to $207m in H1 2024 (+10.1%).
3. Lotto Star
- Blask Index: Decreased from 30.8m in H1 2023 to 29.2m in H1 2024 (-5.2%).
- Market Share: Decreased from 12.70% in H1 2023 to 9% in H1 2024 (-29.1%)
- eFTD: Decreased from 935,000 in H1 2023 to 885,000 in H1 2024 (-5.4%).
- eGGR: Increased from $42m in H1 2023 to $48.2m in H1 2024 (+14.8%).
General iGaming trends and patterns in South Africa
• Significant Market Growth: The South African iGaming industry demonstrated robust growth in H1 2024 compared to H1 2023. The Blask Index increased by 15.6%, rising from an average of 46m in H1 2023 to 53m in H1 2024, indicating an expanding market and greater overall engagement.
• Surge in Player Acquisition: eFTD saw a notable 15.1% increase, climbing from 8.6m in H1 2023 to 9.9m in H1 2024. This growth reflects an effective expansion in player acquisition strategies and a rising interest from new users.
• Revenue Expansion: eGGR grew significantly by 26.8%, from $407m in H1 2023 to $516m in H1 2024. This increase highlights improved financial performance and overall market profitability.
• Emerging Competitive Dynamics: The shifts among the top brands indicate a dynamic and competitive market environment. Betway’s substantial growth contrasts with Hollywoodbets’ and Lotto Star’s challenges in maintaining market share, suggesting a reshuffling in competitive standings. The entrance of EasyBet into the top five further illustrates changing market dynamics and increasing competition.
Shifts among top brands
• Betway emerged as a major player, increasing its market share from 33.85% in H1 2023 to 42.91% in H1 2024. This substantial growth in market share is coupled with significant gains in eGGR, underscoring its strengthened position in the market.
• Hollywoodbets saw a decrease in market share from 45.93% in H1 2023 to 40.21% in H1 2024. Despite a rise in eGGR, this drop suggests increased competitive pressure and challenges in retaining its leading position.
• Lotto Star experienced a decline in market share from 12.70% in H1 2023 to 9% in H1 2024, although its eGGR increased. This indicates that competitive pressures are impacting its market presence despite growth in revenue.
• Supabets saw a minor decrease in market share from 1.89% to 1.50%. While its position remains relatively stable, it has not made significant gains.
• EasyBet entered the top five with a market share of 1%, compared to Tab Gold’s 0.53% in H1 2023. This change reflects a shift in market positioning and the emergence of new competitive players.
Conclusion
Overall, the growth in the South African iGaming market presents opportunities for stakeholders, but also underscores the need for strategic adaptation.
To remain competitive, brands must navigate these shifting dynamics and leverage emerging opportunities effectively.
The promising growth trajectory of the market offers a solid foundation for future expansion, but ongoing strategic adjustments will be essential for sustained success.
Read more from Blask x NEXT.io
Blask x NEXT.io: Nigeria iGaming industry sees growth in H1 2024
Blask x NEXT.io: Ghana iGaming shows signs of decline in H1 2024
Blask x NEXT.io: Political turmoil causes Bangladesh iGaming downturn
About Blask: Founded by visionaries Dmitry Belianin and Max Tesla, Blask is changing the landscape of iGaming analytics. Blask’s mission is to provide cutting-edge, data-driven solutions so market leaders can make quick, informed decisions.

